
பாதுகாப்பு, அபாயம் மற்றும் வரி
Binance Tax India 2026: Transaction History, TDS, Schedule VDA பதிவுகள்
Binance இந்திய crypto tax records-க்கு raw exports, copy-paste ledger, INR valuation, TDS/AIS மற்றும் Schedule VDA evidence pack-ஐ reconcile செய்யும் 2026 workflow.

இந்தியாவில் Binance பயன்படுத்தி crypto வாங்குதல், விற்பனை, swap அல்லது Simple Earn reward பெறுதல் நடந்திருந்தால், tax filing-க்கு ஒரு வருட இறுதி CSV மட்டும் போதாமல் இருக்கலாம். சரியான பதிவு என்பது raw platform export + நீங்கள் உருவாக்கும் transaction-wise ledger + INR valuation evidence + TDS/AIS reconciliation ஆகிய நான்கு அடுக்குகளைக் கொண்டது.
இந்தக் கட்டுரை இந்தியாவில் வசிக்கும் தனிநபருக்கான record-keeping workflow. உங்கள் Earn reward receipt எந்த head-ல் வர வேண்டும், எந்த lot cost ஆக வேண்டும் அல்லது எந்த ITR form பொருந்தும் என்பதை இது தீர்மானிக்காது. அந்த முடிவு உங்கள் facts, residency, activity மற்றும் பொருந்தும் tax year சட்டத்தைச் சாரும்.
Cover-ல் இருப்பது உண்மையான Binance Transaction History interface. அதில் personal transaction rows இல்லாத நிலை பயன்படுத்தப்பட்டுள்ளது; UID, email, balance, address அல்லது token எதுவும் காட்டப்படவில்லை. Menu பெயர் அல்லது export limit மாறலாம் என்பதால், கீழே உள்ள முறை ஒரு குறிப்பிட்ட button path-ஐ நம்பாமல் முழுப் பதிவைச் சேகரிக்க உதவுகிறது.
உள்ளடக்க அட்டவணை
- 2026-ல் எந்த சட்டம், எந்த காலம்?
- Binance-ல் எந்த records export செய்ய வேண்டும்?
- Master ledger-ல் இருக்க வேண்டிய fields
- Copy-paste ledger மற்றும் Binance field mapping
- Schedule VDA மற்றும் TDS reconciliation
- Raw rows முதல் review pack வரை worked case
- மாதாந்திர reconciliation workflow
- Simple Earn reward பதிவுகள்
- AIS, 26AS மற்றும் TIS closure
- Filing முன் இறுதி checklist
2026-ல் எந்த சட்டம், எந்த காலம்?
2026-ல் “current tax law” என்று ஒரே வரியில் சொல்வது தவறாக வழிநடத்தலாம். இந்திய Income-tax Department-ன் புதிய சட்ட வழிகாட்டி இரண்டு காலங்களைத் தெளிவாகப் பிரிக்கிறது:
| நீங்கள் செய்யும் வேலை | பொருந்தும் காலம் | பயன்படுத்த வேண்டிய reference |
|---|---|---|
| FY 2025-26 வருமானத்திற்கான return | 1 ஏப்ரல் 2025–31 மார்ச் 2026; AY 2026-27 | Income-tax Act, 1961 கீழ் notified ITR மற்றும் Schedule VDA |
| 1 ஏப்ரல் 2026க்கு முந்தைய VDA transfer/TDS பதிவு | பழைய சட்டக் காலம் | Section 115BBH, Section 194S மற்றும் தொடர்புடைய guidance |
| 1 ஏப்ரல் 2026 முதல் நடக்கும் transactions | Tax Year 2026-27 | Income-tax Act, 2025 மற்றும் 2026 Rules/current portal instructions |
| 2026 ஜூலை மாதத்தில் AY 2026-27 return file செய்வது | பழைய ஆண்டு பற்றிய filing | Portal இரு சட்டங்களையும் parallel-ஆக handle செய்கிறது; AY 2026-27 old Act forms பயன்படுத்துகிறது |
புதிய Income-tax Act, 2025 1 ஏப்ரல் 2026 முதல் அமலுக்கு வந்தது. அதே நேரத்தில், அதற்கு முன் தொடங்கிய ஆண்டுகளின் return மற்றும் proceedings பழைய Act கீழேயே தொடரும் என்று Income-tax Department கூறுகிறது. ஆகவே July 2026-ல் file செய்கிறீர்கள் என்பதற்காக FY 2025-26 entries-க்கு புதிய section number-ஐ தானாக மாற்ற வேண்டாம்.
115BBH என்ன உறுதி செய்கிறது?
AY 2026-27 filing context-ல் Section 115BBH, VDA transfer-ல் கிடைக்கும் income-க்கு 30% special rate-ஐ குறிப்பிடுகிறது. இது sale proceeds முழுவதின் 30% என்று பொருள் இல்லை; statutory computation transfer income மீது செயல்படும். Cost of acquisition தவிர வேறு expenditure deduction-க்கு கட்டுப்பாடு உள்ளது. VDA transfer loss-ஐ மற்ற income-க்கு set off செய்யவும் அடுத்த ஆண்டுக்கு carry forward செய்யவும் section அனுமதிக்கவில்லை. Applicable surcharge மற்றும் cess தனியாக இருக்கலாம்.
இந்தச் சுருக்கம் tax calculation அல்ல. Acquisition cost தெளிவில்லாத gift, airdrop, reward, inherited asset, P2P அல்லது business activity இருந்தால் professional classification தேவை.
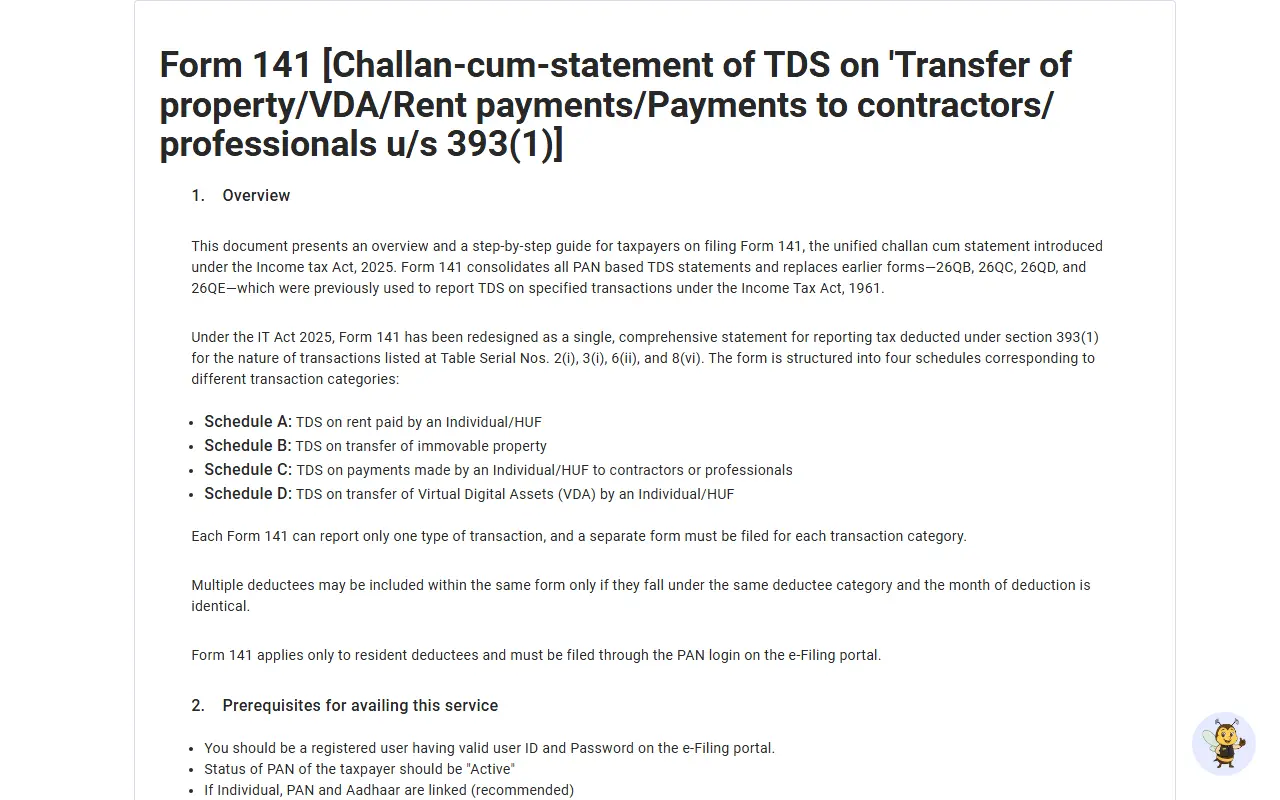
Official-page screenshot: Income Tax Department-ன் public Form 141 guide, VDA transfer TDS-க்கு Schedule D இருப்பதை காட்டுகிறது. இது 1 ஏப்ரல் 2026க்கு பிந்தைய Income-tax Act, 2025 workflow; AY 2026-27 return rows-க்கு இதைத் தவறாகப் பயன்படுத்தக்கூடாது.
1 ஏப்ரல் 2026க்கு பிறகு TDS reference
Income-tax Department tax-payment FAQ படி, credit/payment event 1 ஏப்ரல் 2026 அல்லது அதன் பிறகு இருந்தால் Income-tax Act, 2025-ன் Section 393 கீழ் relevant table item பயன்படுத்தப்படுகிறது. பழைய Act-ல் VDA consideration TDS reference Section 194S. ஒரே ledger-ல் இரண்டையும் கலக்காமல் law_period மற்றும் tds_section_shown columns வைத்தால் portal/statement reference-ஐ சரியாகப் பாதுகாக்கலாம்.
Binance-ல் எந்த records export செய்ய வேண்டும்?
Screenshot வாசிப்பு: இது personal rows இல்லாத உண்மையான Binance Transaction History screen. From/To wallet, time range மற்றும் coin filters ஒரு view-ஐ மட்டும் காட்டலாம்; Spot, Convert, Earn, P2P மற்றும் deposits/withdrawals அனைத்தையும் ஒரே export என்று assume செய்ய வேண்டாம்.
ஒரே “Transaction History” export முழு tax record என்று நினைக்க வேண்டாம். நீங்கள் பயன்படுத்திய product-களுக்கேற்ப பின்வரும் source-களைச் சேகரியுங்கள்:
- Spot trade history: buy, sell, market/limit order, executed quantity, quote amount மற்றும் fee.
- Convert/swap history: ஒரு token மற்றொன்றாக மாறிய நேரம், இரு quantities மற்றும் quote.
- Deposit history: network, quantity, TxID, credited time மற்றும் destination wallet.
- Withdrawal history: network fee, sent quantity, address/TxID மற்றும் status.
- Wallet transfer history: Spot, Funding, Earn அல்லது Margin wallets இடையிலான internal movement.
- Simple Earn history: subscription, redemption, principal return மற்றும் reward distribution.
- P2P/fiat history: பயன்படுத்தியிருந்தால் order, payment currency, counterparty reference மற்றும் bank evidence.
- Referral/rebate/airdrop/distribution: quantity, asset, credit reason மற்றும் timestamp.
- Account statement அல்லது personal-data export: missing category-ஐ கண்டுபிடிக்க cross-check source.
Binance-ன் Privacy Center பற்றிய அதிகாரப்பூர்வ அறிவிப்பு, withdrawal, deposit மற்றும் trading history உட்பட personal transaction data copy download செய்யலாம் என்று விளக்குகிறது. இருப்பினும் feature availability, report frequency மற்றும் menu path account/region/version அடிப்படையில் மாறலாம். Current account UI-ல் கிடைக்கும் source-ஐ பயன்படுத்தி export date-ஐ பதிவு செய்யுங்கள்.
Raw export-ஐ மாற்றாதீர்கள்
Original CSV/ZIP-ஐ read-only archive-ல் வைத்துவிட்டு copy மீது மட்டும் cleanup செய்யுங்கள். Column rename, timezone conversion, row delete அல்லது formula சேர்த்த file raw evidence அல்ல. உதாரண file naming:
binance-spot-orders_2025-04-01T00-00-00+05-30_to_2026-03-31T23-59-59+05-30_exported-2026-07-18.csv
Filename-ல் period, timezone மற்றும் exported date தெரியும். CSV password-protected ZIP-ல் வந்தால் original encrypted file, extraction instructions மற்றும் password storage-ஐ தனித்தனியாக பாதுகாக்கவும். Password அல்லது personal statement-ஐ public cloud link/WhatsApp group-ல் பகிர வேண்டாம்.
Export limit இருந்தால்
Interface ஒரு request-க்கு குறுகிய date range மட்டும் அனுமதித்தால் calendar year-ஐ மாதம்/quarter ஆகப் பிரியுங்கள். எல்லை தேதியில் duplicate அல்லது gap வராமல் inclusive/exclusive timestamps-ஐ note செய்யுங்கள். April 1 midnight boundary மற்றும் UTC-to-IST conversion முக்கியம்.
Master ledger-ல் இருக்க வேண்டிய fields
Clean master ledger-ல் ஒவ்வொரு economically meaningful event-க்கும் ஒரு stable event_id வேண்டும். Platform order ID இல்லாத reward row-க்கு source file + row number + timestamp அடிப்படையில் internal ID உருவாக்கலாம்.
| Field | எதைப் பதிவு செய்ய வேண்டும்? | ஏன் தேவை? |
|---|---|---|
| event_id | மாற்றாத unique ID | duplicate/review tracking |
| law_period | FY 2025-26 / AY 2026-27 அல்லது Tax Year 2026-27 | old/new law boundary audit |
| tds_section_shown | source-ல் தெரியும் 194S / 393(1) Table 8(vi) / not-applicable | சட்ட reference silently மாற்றாமல் இருக்க |
| source_file | raw export filename | audit trail |
| source_row | original row/order ID | evidence-க்கு திரும்பிச் செல்ல |
| timestamp_original | platform காட்டிய நேரம் | source integrity |
| timezone_original | UTC/IST/unknown | date boundary சரிபார்க்க |
| timestamp_ist | converted time | India reporting workflow |
| event_type | buy/sell/swap/reward/deposit/withdrawal/internal transfer | classification review |
| asset_in / qty_in | wallet-ல் உண்மையில் வந்த asset/quantity | quantity reconciliation |
| asset_out / qty_out | wallet-லிருந்து உண்மையில் சென்ற asset/quantity | disposal/fee/TDS analysis |
| gross_qty_in / gross_qty_out | trade contract-ன் pre-fee/pre-TDS quantities | gross vs net settlement proof |
| fee_asset / fee_qty | fee செலுத்திய asset | gross/net வேறுபாடு |
| tds_asset / tds_qty / tds_inr_value | TDS-க்காக பிடித்த asset, quantity மற்றும் INR realization | TDS debit quantity trail |
| inr_value | event நேர INR value | computation evidence |
| valuation_source | exchange pair/rate source + timestamp | reproduce செய்ய |
| acquisition_date | matched lot date | Schedule VDA/cost basis |
| cost_inr | claimed acquisition cost | statutory computation input |
| consideration_inr | transfer consideration | Schedule VDA/TDS check |
| tds_amount | statement-ல் தெரியும் amount | AIS/26AS reconciliation |
| txid_orderid | blockchain TxID/order ID | external evidence |
| classification_status | confirmed/review-required | guesses தவிர்க்க |
| notes | unusual facts | CA review context |
Timestamp rule
Original timestamp-ஐ overwrite செய்யாமல் இரண்டு columns வையுங்கள். உதாரணம்:
- Source: 2026-03-31T20:15:00Z
- IST: 2026-04-01T01:45:00+05:30
இரண்டும் ஒரே instant; ஆனால் India date வேறுபடுகிறது. எந்த date statutory reporting-க்கு பயன்படுத்தப்பட வேண்டும் என்பதை platform display மட்டும் வைத்து ஊகிக்காமல் professional-ஆக உறுதி செய்யுங்கள்.
INR valuation evidence
Crypto-to-crypto swap-ல் INR cash வரவில்லை என்பதால் value zero அல்ல. நீங்கள் தேர்ந்தெடுத்த valuation method-ஐ consistent-ஆக documentation செய்யுங்கள்: எந்த market pair, எந்த exchange, exact timestamp அல்லது reasonable interval, bid/ask/last/weighted price எது என்பதைக் குறிப்பிடுங்கள். இந்தக் கட்டுரை ஒரு valuation method-ஐ tax-approved என்று கூறவில்லை.
Screenshot மட்டும் valuation database அல்ல. Rate source URL/API response, downloaded candle data அல்லது timestamped statement வைத்தால் computation மீண்டும் உருவாக்க முடியும். API key பயன்படுத்தினால் secret, signature மற்றும் unrestricted permissions evidence pack-ல் சேர்க்க வேண்டாம்.
Copy-paste ledger மற்றும் Binance field mapping
Spreadsheet அல்லது CSV editor-ல் முதல் row ஆக கீழே உள்ள header-ஐ copy செய்யலாம். இது tax software schema அல்ல; source evidence இழக்காமல் CA review-க்கு தயாராக்கும் neutral working ledger.
event_id,source_file,source_row,timestamp_original,timezone_original,timestamp_ist,law_period,tds_section_shown,event_type,product,asset_in,qty_in,asset_out,qty_out,gross_qty_in,gross_qty_out,fee_asset,fee_qty,tds_asset,tds_qty,tds_inr_value,inr_value,valuation_source,acquisition_date,cost_inr,consideration_inr,tds_exchange,tds_ais_26as,txid_orderid,classification_status,notes
Binance source → ledger mapping
| Binance/source record | குறைந்தபட்ச ledger fields | event_type | பொதுவான தவறு |
|---|---|---|---|
| Spot trade executions | both assets, gross/net qty, quote, fee, TDS asset/qty/value if shown, order/trade ID, time, law_period | buy/sell | order summary மட்டும் வைத்து partial fills அல்லது TDS debit இழத்தல் |
| Convert/swap history | both gross legs, actual wallet quantities, quote/value, fee/TDS asset trail, order ID, law_period | swap | வந்த token leg அல்லது withholding leg மட்டும் இழத்தல் |
| Exchange TDS/contract note | related order, tds_asset, tds_qty, INR realized, section/date, challan/statement ref | tds_withheld | ₹ TDS மட்டும் வைத்து asset balance reconcile செய்தல் |
| Deposit | asset/qty, network, TxID, credited time, source ownership | external_in / transfer-review | own-wallet transfer-ஐ income என்று auto-label செய்தல் |
| Withdrawal | sent qty, fee asset/qty, network, address, TxID, status | external_out / transfer-review | network fee அல்லது receiving side மறத்தல் |
| Internal wallet transfer | From/To wallet, qty, both timestamps/reference | internal_transfer | Spot→Earn movement-ஐ sale ஆக எண்ணுதல் |
| Simple Earn subscribe | product, principal qty, source wallet, order/reference | earn_subscribe | reward உடன் principal-ஐ merge செய்தல் |
| Simple Earn reward | reward asset/qty, credit time, reward type/reference, INR evidence | earn_reward | annual aggregate மட்டும் வைத்தல் |
| Redemption | principal/reward returned, destination wallet, request/credit time, deduction | earn_redeem | principal return-ஐ புதிய income/sale என்று double count செய்தல் |
| P2P/fiat | asset, fiat amount, order ID, bank reference, fee | p2p_buy/p2p_sell | order மற்றும் bank settlement pair செய்யாதது |
| Referral/airdrop/distribution | asset/qty, reason, credit time, reference | distribution-review | எல்லாவற்றையும் ஒரே reward type ஆக merge செய்தல் |
| Account statement | opening/closing balance, period, wallet | control_total | statement-ஐ transaction-level source என்று கருதுதல் |
P2P evidence pack-ல் unrelated counterparty personal data பகிர வேண்டாம். PAN, bank number மற்றும் address போன்ற sensitive fields-ஐ CA-க்கு least-privilege share செய்யுங்கள்.
மூன்று mechanical checks
1. Source completeness
Raw source rows = mapped ledger rows + documented excluded rows
Cancelled/failed rows exclude செய்தால் source_row, status மற்றும் exclusion reason பதிவு செய்ய வேண்டும். Count silently குறையக்கூடாது.
2. Asset quantity gap
Opening + external in + buys + rewards − sells/swaps out − external out − fees − TDS asset debit − closing = gap
ஒவ்வொரு asset-க்கும் gap zero ஆக வேண்டும்; rounding/dust இருந்தால் exact difference மற்றும் source note தேவை.
3. TDS gap
Exchange/withheld TDS − matched AIS/26AS TDS = open TDS gap
Gap zero என்ற alone tax filing சரி என்று அர்த்தமில்லை. Classification, consideration மற்றும் cost evidence தனியாக complete ஆக வேண்டும்.
Ledger-ready vs filing-ready
Ledger ready ஆக வேண்டுமெனில் source rows map செய்யப்பட்டு quantity gap zero, valuation evidence linked, exceptions தனியாக இருக்க வேண்டும். Filing ready என்று mark செய்ய, கீழே உள்ள values-ல் review-required இருக்கக்கூடாது: income head, acquisition cost, consideration, ITR form, Schedule VDA row treatment, TDS credit. இந்த தீர்மானங்கள் உங்கள் facts-ஐச் சாரும்போது CA sign-off தேவை.
Schedule VDA மற்றும் TDS reconciliation
AY 2026-27 notified ITR material-ல் Schedule VDA ஒவ்வொரு transfer-ஐ transaction-wise fill செய்ய வேண்டும் என்று குறிப்பிடுகிறது. Acquisition date, transfer date, income head, cost of acquisition, consideration மற்றும் transfer income போன்ற fields முக்கியம். Aggregated “annual profit” மட்டும் வைத்தால் இந்த rows-ஐ பின்னர் மீண்டும் உருவாக்க கடினம்.
ஒரு hypothetical ledger example
கீழே உள்ள எண்கள் workflow விளக்கம் மட்டும்; tax advice அல்ல:
| Event | Quantity | INR evidence | Ledger treatment |
|---|---|---|---|
| USDT purchase | 100 USDT | ₹8,400 + fee | acquisition source row |
| Simple Earn subscription | 100 USDT | wallet movement | internal/product movement review |
| Earn reward credit | 0.20 USDT | receipt-time rate retained | receipt classification review |
| Redemption | 100 USDT principal | Spot Wallet return | match against subscription |
| BTC swap | 100.20 USDT out; BTC in | swap-time INR value | potential transfer row; lot mapping required |
Subscription மற்றும் redemption-ஐ இரு sales என்று software auto-classify செய்தால் turnover/income தவறாகலாம். மாறாக USDT→BTC swap-ஐ internal transfer என்று விட்டுவிட்டால் potential transfer row காணாமல் போகலாம். Product label அல்ல, asset ownership/consideration உண்மை மற்றும் law தான் classification-ஐ தீர்மானிக்க வேண்டும்.
TDS final tax அல்ல
Section 194S framework-ல் 1% என்பது consideration-இல் deduction; அது final 30% tax liability அல்லது profit tax calculation அல்ல. TDS வந்ததால் transaction tax-correct என்று அர்த்தமில்லை; TDS வராததால் report செய்ய வேண்டியதில்லை என்றும் அர்த்தமில்லை.
Reconciliation order:
- Exchange/order ledger-ல் gross consideration பார்க்கவும்.
- TDS row அல்லது net settlement difference பார்க்கவும்.
- Form 26AS/AIS/TIS-ல் source, amount மற்றும் date பார்க்கவும்.
- PAN/source mismatch, duplicate அல்லது missing credit-ஐ தனியாக mark செய்யவும்.
- Return prefill-ஐ raw truth என்று ஏற்காமல் உங்கள் complete records உடன் compare செய்யவும்.
Income-tax Department AIS guidance படி taxpayer complete மற்றும் accurate information report செய்வதே பொறுப்பு. AIS/TIS ஒரு cross-check; உங்கள் transaction ledger-க்கு மாற்று அல்ல. Feedback கொடுத்தால் acknowledgement மற்றும் revised status-ஐ evidence pack-ல் வையுங்கள்.
Raw rows முதல் review pack வரை worked case
கீழே உள்ள case முழுவதும் hypothetical. இது tax classification அல்லது filing answer அல்ல; unresolved row எங்கே நிறுத்தப்பட வேண்டும் என்பதை காட்டும் evidence workflow.
Raw evidence inventory
| Raw ID | Source | Event | Evidence value | Law trace |
|---|---|---|---|---|
| R1 | Spot trade export | 100 USDT purchase | ₹8,400; order B1; 2025-04-10T10:00:00+05:30 | FY 2025-26 / AY 2026-27; TDS not-applicable to this buy row |
| R2 | Earn history | 100 USDT subscribe | Spot → Earn movement | FY 2025-26 / AY 2026-27; section not-applicable |
| R3 | Earn history | 0.20 USDT reward | receipt-time value ₹16.80; reward E1 | FY 2025-26 / AY 2026-27; receipt classification review |
| R4 | Earn history | 100.20 USDT redeem | Earn → Spot movement | FY 2025-26 / AY 2026-27; section not-applicable |
| R5 | Convert trade history | gross 100.20 USDT → gross 0.001 BTC | consideration ₹8,500; order C1; 2025-06-30T12:00:00+05:30 | FY 2025-26 / AY 2026-27; Section 194S review |
| R5-TDS | Exchange TDS/contract-note detail | 0.00001 BTC withheld and converted | 1 BTC = ₹85,00,000; TDS INR realization ₹85 | FY 2025-26 / AY 2026-27; Section 194S shown |
| R6 | AIS/26AS export | VDA TDS credit | ₹85; deductor/date reference | AY 2026-27; Section 194S credit |
R1–R6 மற்றும் R5-TDS child evidence original files தனியாக archive செய்யப்பட வேண்டும். ₹85-க்கு 0.00001 BTC என்பது hypothetical exchange-withholding assumption; உங்கள் actual contract note/statement cash, input asset அல்லது output asset எதை debit செய்ததோ அதையே பதிவு செய்ய வேண்டும். கீழே உள்ள ledger அவற்றின் working copy மட்டுமே.
Normalize மற்றும் quantity proof
- R1: law_period = FY 2025-26 / AY 2026-27; asset_in 100 USDT; cost evidence ₹8,400; classification_status = review-required.
- R2: law_period அதே; 100 USDT Spot-இலிருந்து Earn; இரண்டு wallet legs pair செய்து ownership continuity note; tds_section_shown = not-applicable.
- R3: law_period அதே; asset_in 0.20 USDT; inr_value ₹16.80; receipt head மற்றும் acquisition cost = review-required.
- R4: law_period அதே; 100.20 USDT Earn-இலிருந்து Spot; R2 principal + R3 reward-க்கு reconcile.
- R5 trade row: gross_qty_out 100.20 USDT; gross_qty_in 0.001 BTC; asset_out/qty_out 100.20 USDT; asset_in/qty_in 0.001 BTC; consideration ₹8,500; law_period = FY 2025-26 / AY 2026-27; tds_section_shown = 194S.
- R5-TDS debit row: event_type = tds_withheld; asset_out BTC; qty_out 0.00001 BTC; tds_asset BTC; tds_qty 0.00001; tds_inr_value ₹85; related order C1; tds_section_shown = 194S.
- R6: tds_ais_26as ₹85; R5-TDS exchange/contract-note reference-க்கு pair; law_period = AY 2026-27; tds_section_shown = 194S.
USDT quantity check:
Opening 0 + purchase 100 + reward 0.20 − swap out 100.20 = closing 0 USDT
BTC quantity check:
Opening 0 + gross swap credit 0.001 − TDS asset debit 0.00001 = closing 0.00099 BTC
இவை quantity completeness-ஐ காட்டும்; tax treatment சரி என்று நிரூபிக்காது.
Lot working paper — direct ITR row அல்ல
100.20 USDT disposal-ன் ₹8,500 consideration-ஐ quantity basis-ல் working allocation செய்தால்:
| Working lot | Quantity | Allocated consideration | Cost evidence | Provisional status |
|---|---|---|---|---|
| Purchased USDT | 100.00 | ₹8,483.03 | ₹8,400.00 | difference ₹83.03; CA review |
| Reward USDT | 0.20 | ₹16.97 | review-required | transfer income final செய்ய முடியாது |
| Total | 100.20 | ₹8,500.00 | incomplete | unresolved |
இந்த split ஒரு reconciliation working paper மட்டும். Schedule VDA-ல் lot split/aggregation, reward acquisition cost, receipt income head மற்றும் ITR-2/ITR-3 selection-ஐ உங்கள் facts அடிப்படையில் CA/current official instructions உறுதி செய்ய வேண்டும். Reward lot cost unresolved இருக்கும் வரை transfer income total-ஐ final செய்யாதீர்கள்.
TDS reconciliation
Exchange/statement TDS ₹85 − AIS/26AS credit ₹85 = INR gap ₹0
Asset trail: 0.00001 BTC withheld × ₹85,00,000/BTC = ₹85, மேலும் BTC closing quantity 0.00099-க்கு reconcile ஆகிறது. INR gap மற்றும் asset quantity gap இரண்டும் zero ஆன பிறகே R5-TDS pair complete.
Gap zero என்றால் TDS evidence pair ஆனது மட்டும்; final tax liability zero அல்ல. AIS row இல்லாவிட்டால் status = missing-credit, duplicate இருந்தால் duplicate-review, amount/date/PAN வேறுபட்டால் mismatch. Feedback acknowledgement அல்லது deductor correction evidence இல்லாமல் row-ஐ silently force-match செய்ய வேண்டாம்.
Case complete ஆகும் output
- R1–R6 மற்றும் R5-TDS raw/child evidence source-row links.
- USDT gap zero; gross 0.001 BTC → TDS 0.00001 BTC → closing 0.00099 BTC quantity trail.
- R2/R4 internal movement pairing.
- R5 Schedule VDA candidate working row.
- R3 reward classification/cost exception.
- ₹85 TDS amount match + BTC withholding quantity evidence.
- Law audit: FY/AY, 194S/393 section source மற்றும் boundary exceptions.
- CA decision log: reward head/cost, lot method, ITR form, valuation method.
இந்த எட்டில் exception இன்னும் இருந்தால் ledger தயாராக இருக்கலாம்; filing-ready என்று mark செய்யக்கூடாது.
மாதாந்திர reconciliation workflow
Year-end panic தவிர்க்க ஒவ்வொரு மாதமும் இந்த workflow செய்யலாம்.
Step 1: Source inventory
அந்த மாதத்தில் பயன்படுத்திய Binance products மற்றும் external wallets பட்டியல். Spot மட்டும் பயன்படுத்தினீர்கள் என்று நினைத்தாலும் Funding Wallet, Convert, Earn அல்லது distribution row இருக்கிறதா பார்க்கவும்.
Step 2: Normalize, ஆனால் raw-ஐ தொடாதீர்கள்
Working copy-ல் column names, decimal format, asset symbols மற்றும் timestamp format normalize செய்யுங்கள். MATIC/POL போன்ற rename அல்லது token migration இருந்தால் இரண்டையும் ஒரே symbol ஆக அமைதியாக merge செய்யாமல் mapping note வையுங்கள்.
Step 3: Quantity equation
ஒவ்வொரு asset-க்கும்:
Opening quantity + external inflow + buy/reward − sell/spend/external outflow − fee = closing quantity
Wallet-to-wallet internal transfer இருபுறமும் match ஆனால் net zero. Difference இருந்தால் missing file, fee asset, conversion dust, rounding, staking token conversion அல்லது duplicate row பார்க்கவும்.
Step 4: Pair transfers
Withdrawal TxID மற்றும் receiving-wallet deposit TxID match செய்யுங்கள். Same-owner wallet transfer என்று claim செய்வதற்கு இரு addresses-ன் ownership evidence பாதுகாக்க வேண்டும். Address screenshot-ல் முழு balance அல்லது seed phrase காட்ட வேண்டாம்; TxID public explorer evidence போதுமான சூழல் இருக்கலாம்.
Step 5: Lot and valuation review
Software auto-selected cost basis method-ஐ blind-ஆக accept செய்யாதீர்கள். இந்திய சட்டத்தில் உங்கள் facts-க்கு பொருந்தும் identification/computation-ஐ CA உறுதி செய்ய வேண்டும். Unmatched disposal-ஐ zero cost என்று தானாக final செய்யாமல் review-required என்று வையுங்கள்.
Step 6: Exception report
இந்த rows மட்டும் மனித review-க்கு அனுப்புங்கள்:
- negative balance அல்லது impossible quantity;
- missing acquisition;
- swap-ல் ஒரு leg மட்டும்;
- reward reason தெரியாத distribution;
- TDS amount/date mismatch;
- TDS INR row உள்ளது, ஆனால் tds_asset/tds_qty அல்லது gross/net settlement evidence இல்லை;
- law_period இல்லை அல்லது timestamp-க்கு பொருந்தாத 194S/393 section காட்டுகிறது;
- March 31/April 1 timezone boundary;
- token rename/migration;
- failed/cancelled order completed என்று வந்தது;
- P2P bank amount மற்றும் order amount வேறுபாடு;
- duplicate export overlap.
Step 7: Freeze the month
Reconciled file version, exception notes, source list மற்றும் generated timestamp சேமியுங்கள். பின்னர் edit செய்தால் version number உயர்த்தவும்; பழைய version delete செய்ய வேண்டாம். SHA-256 checksum போன்ற integrity record optional ஆனால் useful—அது tax correctness-ஐ நிரூபிக்காது, file மாறாததை மட்டும் காட்டும்.
Simple Earn reward பதிவுகள்
Simple Earn-ல் குறைந்தது மூன்று வேறு events இருக்கலாம்: subscription, periodic reward, redemption. Locked early redemption, Auto-Subscribe அல்லது reward asset வேறுபாடு இருந்தால் கூடுதல் rows வரும்.
Reward receipt row
ஒவ்வொரு credit-க்கும் asset, quantity, credited timestamp, product, reward type, source history row மற்றும் அந்நேர INR valuation evidence வைத்திருங்கள். “மொத்த ஆண்டு reward = 12 USDT” என்ற aggregate, later disposal cost/acquisition date map செய்ய போதாது.
Principal movement
Spot Wallet-இலிருந்து Earn position-க்கு principal சென்றது asset sale-ஆ இல்லையா என்பதை software label மட்டும் தீர்மானிக்க விடாதீர்கள். Quantity மற்றும் ownership continuity-ஐ document செய்து review செய்யுங்கள். Simple Earn redemption வழிகாட்டி product history மற்றும் wallet return flow-ஐ புரிய உதவும்; அது tax classification அல்ல.
Reward later sold or swapped
Reward receipt classification மற்றும் reward asset-ன் பின்னர் transfer ஆகியவை இரண்டு தனி tax questions ஆக இருக்கலாம். அதனால் receipt-time value, later consideration மற்றும் acquisition basis அனைத்தையும் வைத்திருங்கள். Section 115BBH transfer rules இருப்பதால் later sale/swap row காணாமல் போகக்கூடாது; ஆனால் receipt-time head-ஐ இந்தக் கட்டுரை ஊகிக்கவில்லை.
APR screenshot போதுமா?
இல்லை. Displayed APR variable ஆக இருக்கலாம்; actual credited quantity தான் ledger source. APR calculator guide estimate மற்றும் actual reward reconciliation-ஐப் பிரிக்கிறது. Product card screenshot-ஐ secondary evidence ஆக வைத்தாலும் Earn History export/statement-ஐ முதன்மையாகப் பயன்படுத்துங்கள்.
AIS, 26AS மற்றும் TIS closure
AIS/TIS/26AS ஒரே பொருள் அல்ல; exchange history-க்கும் அவை மாற்று அல்ல. Current Income Tax portal-லிருந்து relevant assessment year documents-ஐ எடுத்து, ஒவ்வொரு VDA/TDS source-ஐ ledger-க்கு match செய்யுங்கள்.
| Portal evidence | Ledger-ல் match செய்ய வேண்டியது | Closure status |
|---|---|---|
| AIS information row | source/deductor, transaction nature, amount, date | matched / mismatch / duplicate / missing |
| TIS derived value | AIS processing summary | explanation-only; raw transaction substitute அல்ல |
| Form 26AS TDS credit | deductor, section/reference, TDS amount | matched / credit-missing / wrong PAN/date |
| Exchange TDS/contract note | order, gross consideration, TDS asset/qty/INR realized, section/date | AIS/26AS pair + asset quantity trail அல்லது exception |
| Feedback acknowledgement | submitted feedback ID/status | open / accepted / modified / rejected |
Closure steps
- AY 2026-27 documents மற்றும் Binance/export period இரண்டும் FY 2025-26 boundary-க்கு பொருந்துகிறதா உறுதி செய்யுங்கள்.
- Exchange TDS rows-ஐ order ID/date/amount மட்டுமல்லாமல் law_period, section, gross/net quantities, tds_asset மற்றும் tds_qty மூலம் ledger event-க்கு link செய்யுங்கள்.
- AIS/26AS source, PAN/deductor, amount மற்றும் date compare செய்யுங்கள்.
- Match இல்லாத ஒவ்வொரு row-க்கும் missing-credit, amount-mismatch, date-mismatch, duplicate அல்லது unidentified-source status கொடுக்கவும்.
- Portal feedback கொடுத்தால் acknowledgement, submitted value, reason மற்றும் latest status export/screenshot சேமிக்கவும்.
- Deductor correction தேவைப்பட்டால் communication/reference வைத்திருங்கள்; உங்கள் working file-ல் official record மாறியது போல overwrite செய்யாதீர்கள்.
- Filing working copy உருவாக்கிய தேதியில் AIS/26AS/TIS மீண்டும் download செய்து version/date பதிவு செய்யுங்கள்.
Closure complete என்றால் ledger TDS total, exchange statement total, AIS/26AS matched total மற்றும் open exceptions count நான்கும் README-ல் இருக்க வேண்டும். Open exceptions 0 அல்லாதபோது CA/official portal guidance இல்லாமல் credit-ஐ ஊகித்து claim செய்ய வேண்டாம்.
Filing முன் இறுதி checklist
Data completeness
- FY 2025-26க்கு 1 ஏப்ரல் 2025 முதல் 31 மார்ச் 2026 வரை முழு exports உள்ளனவா?
- UTC/IST boundary transactions இருபுறமும் சோதிக்கப்பட்டதா?
- Spot, Convert, Earn, Funding, P2P, deposit/withdrawal அனைத்தும் inventory-ல் உள்ளனவா?
- External wallet TxID மற்றும் ownership notes உள்ளனவா?
- Reward/rebate/airdrop rows தனியாக உள்ளனவா?
- Raw files மாற்றாமல் archive செய்யப்பட்டுள்ளனவா?
Computation review
- ஒவ்வொரு transfer-க்கும் acquisition date/cost evidence உள்ளதா?
- Crypto-to-crypto swap மற்றும் stablecoin disposal மறக்கப்படவில்லையா?
- Fee asset quantity equation-ல் உள்ளதா?
- Valuation source/method consistent-ஆக documented-ஆ?
- Loss set-off/carry-forward treatment 115BBH-க்கு எதிராக இல்லையா?
- Earn receipt classification guess இல்லாமல் reviewed-ஆ?
TDS and filing
- Exchange statement, Form 26AS, AIS மற்றும் TIS compare செய்யப்பட்டதா?
- 1% TDS-ஐ final tax என்று தவறாக எடுத்துக்கொள்ளவில்லையா?
- AY 2026-27 old Act form மற்றும் 1 ஏப்ரல் 2026க்கு பிந்தைய new Act records கலக்கவில்லையா?
- Schedule VDA transaction-wise rows ledger-ல் இருந்து reproduce ஆகிறதா?
- பயன்படுத்தும் ITR form current official portal/instructions மூலம் உறுதி செய்யப்பட்டதா?
- CA-க்கு unresolved exception list கொடுக்கப்பட்டதா?
Privacy and security
Tax file-ல் PAN, address, balance மற்றும் transaction history போன்ற sensitive data இருக்கும். Public screenshot, shared drive அல்லது support chat-ல் full statement upload செய்ய வேண்டாம். API secret, session Cookie, 2FA code, authenticator setup key அல்லது seed phrase tax evidence அல்ல. Binance account security checklist access control மற்றும் device review-ஐ விளக்குகிறது.
CA-விடம் கொடுக்க வேண்டிய evidence pack
ஒரு clean folder structure review நேரத்தை குறைக்கும்:
- 01-raw-binance-exports/
- 02-external-wallet-and-bank/
- 03-master-ledger/
- 04-valuation-evidence/
- 05-tds-ais-26as/
- 06-schedule-vda-working/
- 07-review-required/
- 08-filed-return-and-acknowledgement/
README-ல் taxpayer period, timezone, platforms, wallets, valuation method, ஒவ்வொரு period-க்கும் law_period → tds_section_shown mapping, TDS INR total + asset/quantity trail, unresolved issues மற்றும் last updated RFC3339 timestamp எழுதுங்கள். Password-ஐ அதே folder-ல் plain text ஆக வைக்க வேண்டாம். CA-க்கு least-privilege share மற்றும் expiry date பயன்படுத்துங்கள்.
FAQ: அடிக்கடி கேட்கப்படும் கேள்விகள்
Binance CSV tax report-க்கு போதுமா?
பொதுவாக அது ஒரு source மட்டுமே. Earn, Convert, P2P, wallet transfer, deposit/withdrawal மற்றும் external-wallet records தனியாக இருக்கலாம். Schedule VDA rows உருவாக்க acquisition cost மற்றும் INR evidence கூட தேவை.
1% TDS செலுத்தியதால் வேறு tax இல்லைதானே?
இல்லை. TDS consideration மீது credit/deduction mechanism; final liability computation வேறு. 115BBH framework, applicable surcharge/cess மற்றும் TDS credit-ஐ தனித்தனியாக reconcile செய்ய வேண்டும்.
Crypto loss salary அல்லது share profit-க்கு set off செய்யலாமா?
Section 115BBH VDA transfer loss set-off மற்றும் carry-forward-ஐ கட்டுப்படுத்துகிறது. உங்கள் exact rows மற்றும் income head-ஐ professional-ஆக review செய்யுங்கள்; software net annual result மட்டும் நம்ப வேண்டாம்.
Own wallet transfer Schedule VDA-ல் வருமா?
Ownership மாறாத movement மற்றும் asset swap ஒன்றல்ல. இரு wallet sides, TxID, fee மற்றும் ownership evidence வைத்திருந்து legal classification உறுதி செய்யுங்கள். Internal transfer label மட்டும் போதாது.
Simple Earn reward எப்போது taxable?
Receipt மற்றும் later transfer treatment facts-ஐச் சாரலாம். Reward credit timestamp/value மற்றும் later disposal இரண்டையும் பதிவு செய்து CA-யிடம் classification உறுதி செய்யுங்கள்; பொதுவான article-இல் ஒரே answer கூறுவது பாதுகாப்பானதல்ல.
எத்தனை வருடம் records வைத்திருக்க வேண்டும்?
ஒரே universal number இங்கு கூறவில்லை. Applicable assessment/reassessment, appeal மற்றும் பிற சட்ட retention periods உங்கள் சூழலைச் சாரலாம். CA-விடம் retention policy எழுதிக் கொண்டு, active proceedings முடிவதற்கு முன் source files delete செய்யாதீர்கள்.
சரிபார்க்கப்பட்ட அதிகாரப்பூர்வ ஆதாரங்கள்
- Income Tax Department — AY 2026-27 ITR-2 online manual மற்றும் Schedule VDA
- Income Tax Department — Form 141, Section 393(1) Schedule D VDA TDS guide
- Income Tax Department — Section 115BBH
- Income Tax Department — Section 194S VDA TDS
- CBDT Circular 13/2022 — Section 194S exchange transactions guidance
- Income Tax Department — AIS/TIS guidance
- Income Tax Department — New Act transition and parallel years
- Income Tax Department — TDS compliance after 1 April 2026
- Binance — Privacy Center personal transaction-data download
வெளிப்படுத்தல் மற்றும் அபாய எச்சரிக்கை
இந்தத் தளத்தில் சில தேர்ந்தெடுக்கப்பட்ட பக்கங்களில் affiliate/referral இணைப்புகள் இருக்கலாம். அவற்றின் மூலம் தளத்திற்கு கமிஷன் கிடைக்கலாம்; அது tax record workflow, சட்ட ஆதாரம் அல்லது ஆசிரியத் தீர்ப்பை மாற்றாது. இந்தப் பக்கத்தில் registration referral link இல்லை.
இது கல்வி மற்றும் record-keeping தகவல் மட்டுமே; நிதி, முதலீட்டு, சட்ட அல்லது வரி ஆலோசனை அல்ல. Tax law, forms மற்றும் portal workflow மாறலாம். Filing அல்லது TDS action முன் current official instructions மற்றும் இந்திய Chartered Accountant/தகுதியான tax professional மூலம் உங்கள் facts-ஐ review செய்யுங்கள். முழு ஆசிரியக் கொள்கை மற்றும் வெளிப்படுத்தல்.